Insights from the latest EPC Fraud Trends Report (3): Instant Payments under the lens
Instant payments continue to transform how individuals and businesses move money. But as highlighted in the EPC 2025 Payments Threats & Fraud Trends Report, they also introduce new and unique risks. Fraudsters thrive in environments where funds move fast, and SCT Inst provides exactly that.
In this final article of our series, we explore why instant payments require new approaches to fraud prevention and how combining Verification of Payee (VOP) with real‑time fraud intelligence can significantly strengthen PSP resilience.
Instant Payments: Convenience Meets Vulnerability
The main appeal of SCT Inst is its speed. Money is transferred and made available within seconds. But this same speed is what makes it so attractive to criminal networks. According to the EPC report, once a victim is convinced to initiate a fraudulent payment, the funds can be withdrawn or moved across multiple mule accounts almost instantly.
This drastically reduces the chances of recovery.
Social Engineering + SCT Inst = High-Impact Fraud
The EPC warns that the majority of losses linked to instant payments originate from social‑engineering‑based APP fraud.
Criminals pressure or manipulate victims into making payments that settle instantly. This includes fake invoice payments, supplier impersonation, fraudulent “safe account” transfers, QR-code‑based payment diversions and fake government or bank payment instructions.
Strong authentication is not enough when the user wants to make the payment — because they believe they’re doing the right thing.
Mule Networks Are Becoming Faster and More Professional
Another critical insight from the EPC report: mule accounts are evolving into sophisticated networks.
Classic flow: Frauster hires and instructs a mule and makes a fraudulent transfer to the mule’s account. Mule withdraws amount in cash and gives it to the fraudster.
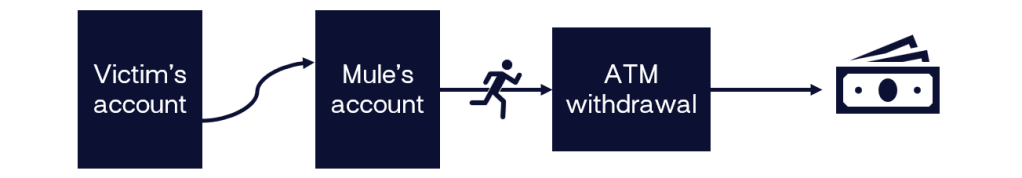
Figure 1: Classic money mule flow
Classic upscaled: Frauster hires and instructs many mules and enables a huge fraudulent transfer to first mule’s account. Amount is too big for just one cash-out and many second level mules are involved.
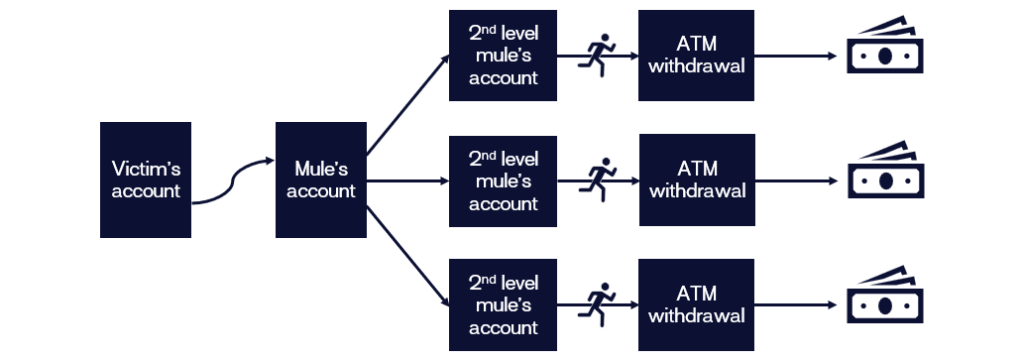
Figure 2: Classic upscaled money mule flow
Criminals utilise multiple account layers, automated routing patterns, cross-border fund movements and/or mules sourced as a service (“money-muling-as-a-service”). Instant payments allow them to execute schemes with less friction and far greater speed.
Why PSPs Need Real-Time, Intelligence-Driven Fraud Detection
The report clearly stresses that fraud mitigation for instant payments must be real-time, context-aware and supported by external intelligence.
Traditional systems based on historical behaviour or batch analysis cannot keep pace with multi-layered attacks carried out in seconds.
This is where modern intelligence feeds come into play.
How LUXHUB Helps PSPs Detect Fraud Faster
LUXHUB’s Fraud Intelligence Gateway enhances PSP fraud defences in ways that are specifically aligned with the challenges described in the EPC report. The platform notably enables a secure connection to the Banque de France’s National File of Accounts Reported for Fraud Risk (FNC‑RF)
The Fraud Intelligence Gateway provides:
- Real-Time Fraud Signals: early warning indicators of emerging scams, mule activity, and compromised accounts.
- Market-Wide Intelligence: Fraud patterns seen across various French PSPs, not just at one institution, offering a broader detection net.
Why VOP + FNC‑RF is the Strongest Combination for Credit Transfers
Together, Verification of Payee and FNC-RF address the most common failure points described in the EPC report:
- Before the payment: VOP checks whether the payee details actually match, reducing invoice fraud and IBAN manipulation.
- During the payment: Real-time fraud intelligence identifies anomalies that might indicate social engineering or mule activity.
- After the payment: Faster detection increases the chance of freezing funds before they move again (still challenging, but essential in SCT Inst environments).
This combination gives PSPs a multilayered defence adapted to the speed of modern payments.
Instant payments deliver clear benefits to consumers and businesses but they also expand the window of opportunity for fraudsters.
The EPC 2025 Fraud Trends Report highlights that the future of fraud prevention is:
- real-time,
- intelligence-driven,
- collaborative,
- and deeply integrated into the customer experience.
By deploying both VOP and FNC‑RF, PSPs can significantly reduce their exposure to APP fraud, mule networks, and social engineering attacks while strengthening customer trust in instant payments.